Big Jobs Number, Economic Growth Pushing Rates Higher
By Lyon Wealth Management on October 10, 2023
1. Labor Momentum. Last week, September JOLTs (job openings) and weekly initial claims both reported better than expected. There are currently 1.5 jobs open for every unemployed person – meaning that the labor market remains tight. The job openings data continued to show strength, rebounding across many sectors, including manufacturing, business services, finance, and health and education services. The initial unemployment claims four-week moving average remains at very low levels, well below recessionary levels. Finally, the Challenger Gray Jobs Report indicated companies expect to continue hiring – last month increased by 55% from last year’s level.
Chart 1: Nonfarm Payrolls and Initial Claims Data Remains Elevated, Better Than Expected1
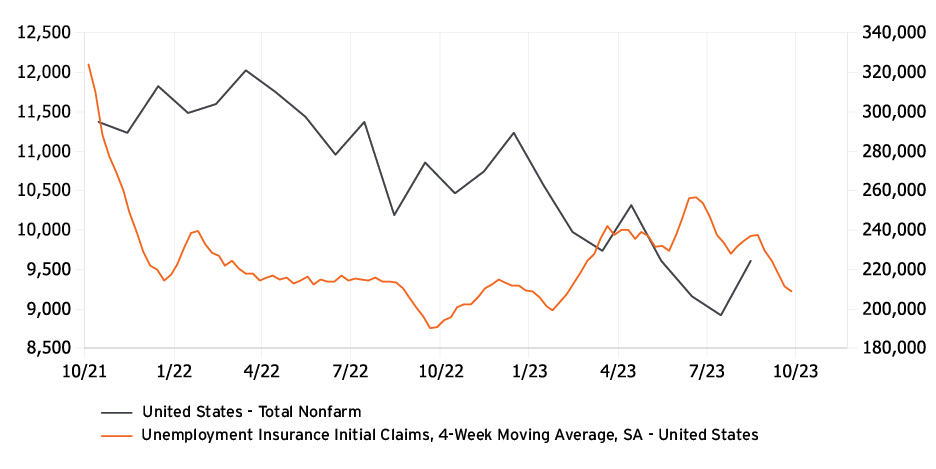
As we have been highlighting for over a year, a strong labor market and higher wages are very good for the consumer (75% of GDP), confidence and the overall economy. At the same time, the nonfarm payroll report showed average hourly earnings (AHE) at above average levels, yet not accelerating, which indicates progress toward curbing overall inflation.
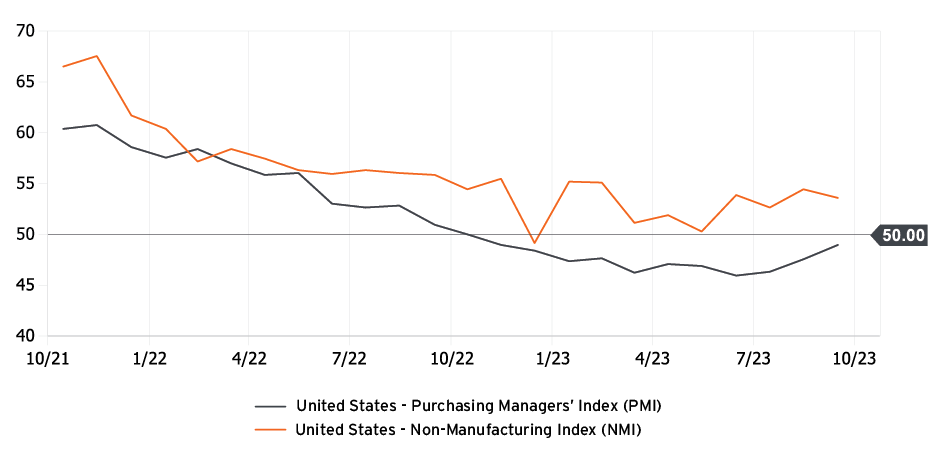
Beyond the labor market, ISM’s manufacturing and services PMI data continued to show momentum in the economy, driven by new orders, strong employment, higher prices, better inventories and overall business activity.
Chart 2: Resilient Economic Indicators2
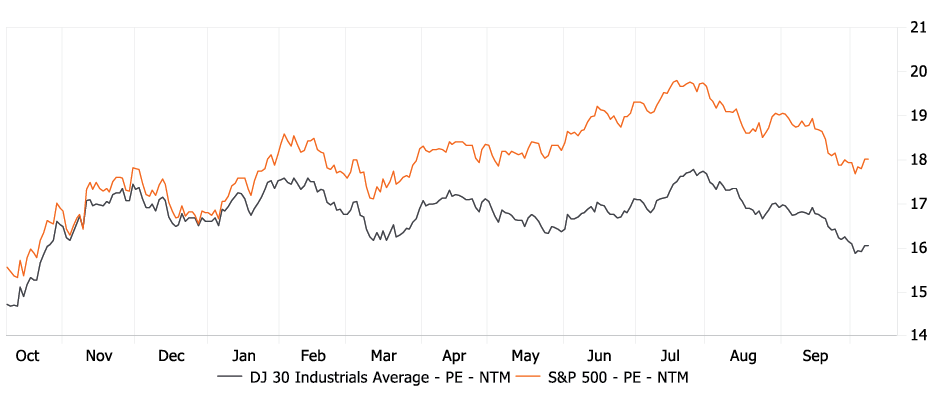
2. Putting Cash to Work. Valuations and sentiment have both pulled back, and overall market sentiment has weakened as of late. Not surprisingly, this coincides with the historically most volatile time of the year in markets: August/September and the first part of October. We see opportunities in a variety of sectors and the overall equity and fixed income markets as we approach the strongest period of the year: October to December. We continue to like energy, discretionary, industrial and technology sectors. We also see select opportunities in healthcare. Now is not the time to be negative with these oversold conditions – it is important to think long-term. We continue to add to high-quality, blue chip companies with strong free cash flow, cheap valuations and dividend growth opportunities.
Chart 3: Valuation Adjustments Create a Buying Opportunity in Equities3
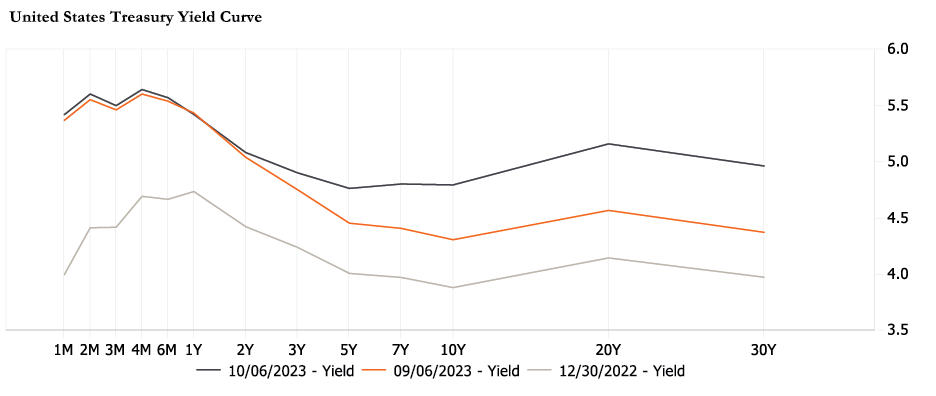
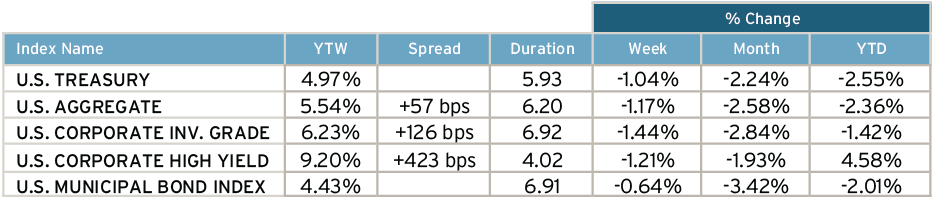
3. Bonds: Prices Lower, Yields Higher. A combination of U.S. quantitative tightening (QT) policy for the foreseeable future and China’s influence has caused higher yields and lower bond prices. Sentiment is quite negative overall for fixed income, which poses an opportunity for long-term investors. It’s been a very long time (over a decade) since there has been competition to equities. With the 4-year municipal bond at 4% (6% tax equivalent) and a 4-year corporate bond at 6.1%, we see opportunities for higher yielding instruments.
Chart 4: Yield Curve Continues to Move Higher4
4. Israel at War. Hamas’ terror attack on Israel will have broad implications for middle east relations. The surprise attack towards Israel, coordinated by Hamas and supported by Iran, went undetected by Israeli and international intelligence. It is the most significant breach of Israel’s borders since 1973 and has resulted in hundreds of Israeli civilians killed and taken hostage.5 This attack comes just weeks after the U.S. unfroze $6 billion in assets for Iran.
U.S. officials flew to Saudi Arabia to speed up ongoing negotiations between Israel, Saudi Arabia and the United States. The talks are centered on Saudi Arabia normalizing its relations with Israel in return for U.S. weapon sales. Saudi Arabia has not recognized Israel since its founding in 1948; a deal could revamp the geopolitics in the Middle East, largely at the expense of Iran and other Middle Eastern nations with Iranian-backed militias. It is worth noting that Saudi Arabia and Iran restored ties back in March, with negotiations brokered by China. Saudi Arabia is playing the “peacekeeper” role, while building its influence beyond the Middle East.
Saudi Arabia has indicated a willingness to increase its output of oil if prices move too high. Its oil production decisions are still based on economic motivations. Saudi Arabia’s ability to raise output is complicated by its relations with Moscow; both of which have moved in lockstep to keep prices high and restrict production.
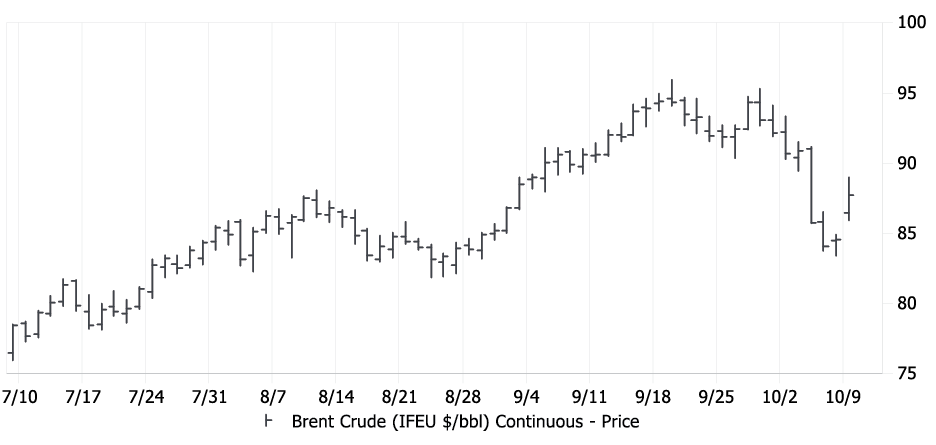
OPEC+ forecasters predict a global deficit of 3.3 million barrels a day in the fourth quarter, and many expect Brent Crude Oil prices to top $100.
While a tragic event with an ultimately unknown outcome, from an investment point of view, we believe this will create a flight to safety in risk assets and is the main reason the U.S. equity markets rallied today. The bond market was closed.
Chart 5: Oil Price Risk Is to the Upside6
5. The Week Ahead.
Earnings – Tuesday: PEP; Thursday: DPZ, WBA, DAL; Friday: BLK, JPM, UNH, WFC, C, PNC.
Economics – Wednesday: PPI (September), FOMC Minutes; Thursday: CPI (September)
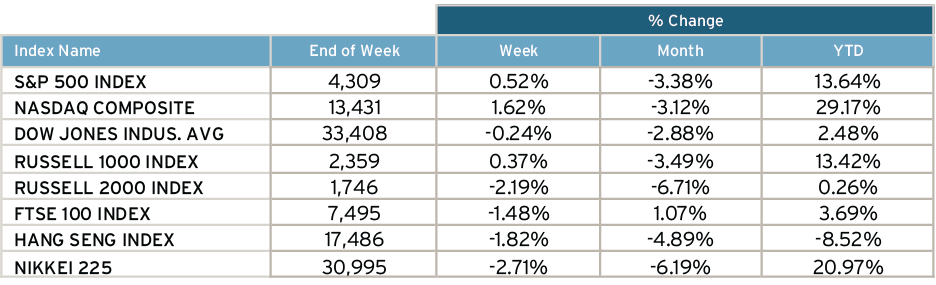
Return for Selected Indices7
Subscribe to Our Newsletter!
Lyon Wealth Management is a group comprised of investment professionals registered with Hightower Advisors, LLC, an SEC registered investment adviser. Some investment professionals may also be registered with Hightower Securities, LLC (member FINRA and SIPC). Advisory services are offered through Hightower Advisors, LLC. Securities are offered through Hightower Securities, LLC.
This is not an offer to buy or sell securities, nor should anything contained herein be construed as a recommendation or advice of any kind. Consult with an appropriately credentialed professional before making any financial, investment, tax or legal decision. No investment process is free of risk, and there is no guarantee that any investment process or investment opportunities will be profitable or suitable for all investors. Past performance is neither indicative nor a guarantee of future results. You cannot invest directly in an index.
These materials were created for informational purposes only; the opinions and positions stated are those of the author(s) and are not necessarily the official opinion or position of Hightower Advisors, LLC or its affiliates (“Hightower”). Any examples used are for illustrative purposes only and based on generic assumptions. All data or other information referenced is from sources believed to be reliable but not independently verified. Information provided is as of the date referenced and is subject to change without notice. Hightower assumes no liability for any action made or taken in reliance on or relating in any way to this information. Hightower makes no representations or warranties, express or implied, as to the accuracy or completeness of the information, for statements or errors or omissions, or results obtained from the use of this information. References to any person, organization, or the inclusion of external hyperlinks does not constitute endorsement (or guarantee of accuracy or safety) by Hightower of any such person, organization or linked website or the information, products or services contained therein.
Click here for definitions of and disclosures specific to commonly used terms.
1550 Tiburon Blvd
Suite B Up #6
Tiburon, CA 94920
(415) 702-1622
Legal & Privacy
Web Accessibility Policy
Form Client Relationship Summary ("Form CRS") is a brief summary of the brokerage and advisor services we offer.
HTA Client Relationship Summary
HTS Client Relationship Summary
Hightower Advisors, LLC is a SEC registered investment adviser. Registration as an investment adviser does not imply a certain level of skill or training. Some investment professionals may also be registered with Hightower Securities, LLC and offer securities through Hightower Securities, LLC, member FINRA/SIPC. You can check the background of our firm and investment professionals on brokercheck.finra.org. Unless otherwise indicated relative to a specific award or ranking, Hightower Advisors, LLC does not pay a fee to be considered for any ranking or recognition, but may have paid to publicize rankings obtained and disseminated prior to 11.4.2022. All awards / rankings / ratings obtained and distributed on or after 11.4.2022 will be accompanied by specific disclosure as applicable.
© 2026 Hightower Advisors. All Rights Reserved.